Treasury Auction: 3-Year Notes Clear at 4.627% With 2.53 Cover
Monday's $58 billion 3-year Treasury auction cleared at 4.627%, below October's 4.932%, with a 2.53 bid-to-cover and more direct-bidder demand before CPI.
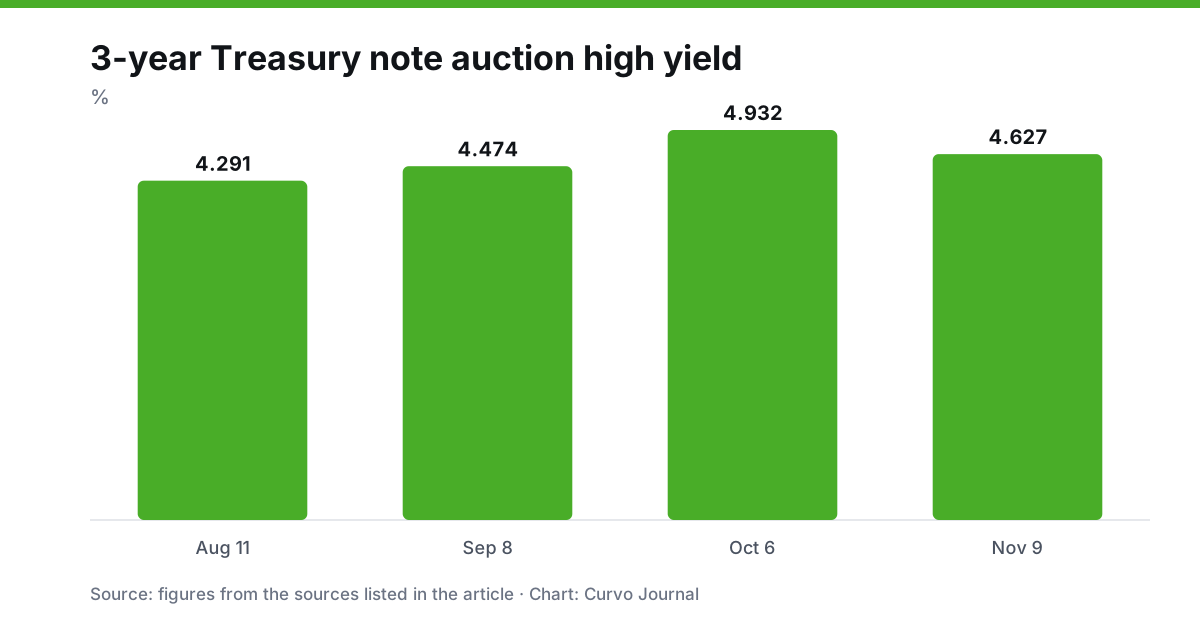
NEW YORK — The Treasury opened its November refunding on Monday with a $58 billion sale of three-year notes that cleared at a high yield of 4.627%, a little above the 4.625% coupon the notes will carry. The auction drew a bid-to-cover ratio of 2.53, the first read on demand for the week’s $125 billion of coupon supply.
The 3-year Treasury auction is the smallest-duration piece of the refunding and the one most closely tied to expectations for the Federal Reserve’s policy rate. Its result lands a day before the October consumer price report and the 10-year sale.
The numbers
The notes are a new issue maturing November 15, 2029, and settle on November 16. Bidders at the high yield were allotted 73.41% of the amount they bid for. The median accepted yield was 4.580% and the lowest accepted yield 4.500%.
Awards were distributed as follows, in competitive bids unless noted:
- Direct bidders took $20.2 billion.
- Indirect bidders took $32.0 billion, plus $184 million in noncompetitive awards.
- Primary dealers took $5.5 billion.
Federal Reserve accounts also took about $11.8 billion of noncompetitive awards on top of the $58 billion offering, a rollover of maturing securities that is excluded from the announced offering size.
How it compares with recent sales
Against the previous three monthly 3-year auctions, the November sale was a mixed picture. The yield was lower than October’s 4.932% but above September’s 4.474% and August’s 4.291%. The bid-to-cover of 2.53 was the lowest of the four: the earlier sales covered 2.62 in October, 2.72 in September and 2.71 in August.
The buyer mix shifted. Direct bidders took more than in any of those sales, up from $18.0 billion in October and $13.8 billion in August, while primary dealers, the buyers of last resort, were left with about 9% of the offering against nearly 12% in August. Indirect bidders still took the majority, a little more than 55%. Indirect awards include foreign central banks but also many domestic funds that bid through dealers, so the figure is not a clean measure of foreign demand.
Why the short end matters here
Three-year yields move with the market’s view of where short-term rates are heading. The coupon on the new notes, 4.625%, compares with 4.250% on the August issue, which shows how far the rate backdrop has shifted over a single quarter, even though October’s auction cleared higher still.
A lower yield than October’s does not by itself signal easier conditions. It reflects where the market stood on Monday afternoon, and the October consumer price report, due Tuesday, can move it quickly in either direction.
What to watch
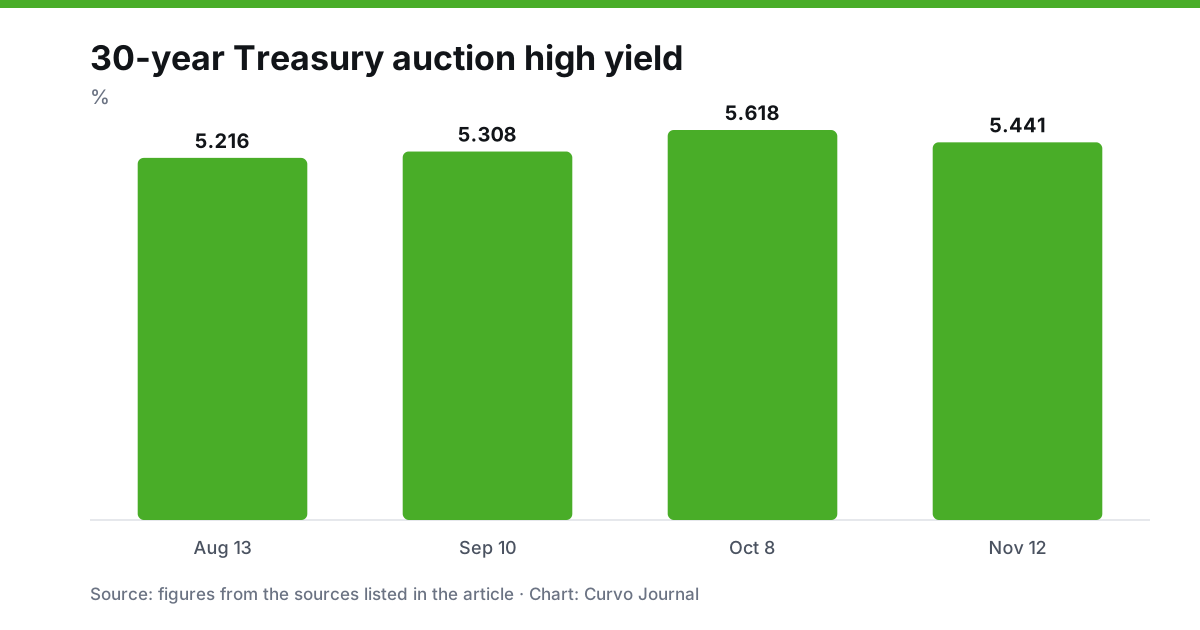
The 10-year auction on Tuesday is a new $42 billion issue, and the 30-year on Thursday is $25 billion. Dealers will compare their bid-to-cover and award splits against Monday’s: a similar pattern of firmer direct demand and lighter dealer takedown would suggest the buyer base is holding up through the week.
Prepared with AI assistance from public sources and reviewed under our editorial policy. Not investment advice.